
Banks will literally pay you hundreds of dollars just to open an account. Not in points, not in miles — in cold, hard cash deposited straight into your new checking account. In October 2026, the offers range from $200 to $900 for mainstream accounts, with a few eye-popping outliers reaching $1,500.
Here’s the math that makes bonus hunting the highest-paid hobby in personal finance. Open three accounts over a year — say Chase ($400), SoFi ($400), and Wells Fargo ($500) — meet the requirements, and you’ve earned $1,300 for maybe 3 hours of total effort. That’s over $400/hour. No side hustle, no overtime, no selling anything.
But here’s what the generic “top 10 bonuses” lists won’t tell you: the biggest number isn’t always the best deal. A $1,500 bonus that requires parking $200,000 for months is worse than a $250 bonus you earn with two paychecks. So instead of sorting by bonus size like everyone else, I ranked these 10 offers by bonus-hunter strategy — easiest, biggest, fastest — so you can pick the ones that fit YOUR situation.
Honesty note: every bonus below was verified against bank-published terms as of October 2026. Offers change or expire without notice — always confirm the current terms on the bank’s site before applying.
Related Guides
- Best High-Yield Savings Accounts 2026 — park your bonus winnings somewhere earning 4%+ instead of 0.01%.
- No Credit Check Bank Accounts 2026 — denied by ChexSystems? Start here.
- Emergency Loans With No Credit Check — a $500 bonus beats a $500 emergency loan every time.
- How to Build Wealth Slowly — bonuses are a head start, not a wealth plan.
Helpful Official Resources
- FDIC — BankFind — verify any bank’s insurance before depositing.
- Consumer Financial Protection Bureau — guides on account fees and your banking rights.
- IRS — Bank Bonuses & Taxes — interest and bonus income is taxable; see 1099-INT rules.
The 10 Best Checking Account Bonuses, Ranked by Hunter Strategy
1. Best overall combo: Chase — $400 checking (or $900 with savings)
The king of bank bonuses. Chase Total Checking pays $400 for setting up direct deposit — no minimum amount specified, just get it done. But the real play is the combo: add a savings account with a $200 bonus and Chase throws in an extra $400, for $900 total. That’s the biggest realistically-achievable haul from a single bank.
Requirements: Direct deposit set up (no stated minimum for the $400); savings combo needs $15,000+ in new money for 90 days for the full stack.
Payout: Typically within 10 business days of meeting requirements.
Best for: Anyone who can move direct deposit — the best effort-to-reward ratio in banking.
Trap to avoid: The $15 monthly service fee — waivable with $500+ monthly direct deposit, a $1,500 balance, or a linked account. Don’t let fees nibble the bonus.
2. Easiest requirements: Capital One 360 Checking — $250
No branches, no nonsense: deposit $500+ in direct deposits twice within 75 days and pocket $250. That’s it. No balance tiers, no debit-card transaction quotas, no monthly fees to dodge. This is the bonus you recommend to your skeptical friend who thinks there’s always a catch.
Requirements: Two direct deposits of $500+ within 75 days of opening.
Payout: Fast — historically one of the quickest posters.
Best for: First-time bonus hunters; anyone without huge paychecks.
Trap to avoid: None major — this is genuinely one of the cleanest offers in banking.
3. Biggest headline (read the fine print!): Citibank — up to $1,500
Yes, $1,500 is real. It’s also a masterclass in reading requirements: the top tier demands $200,000 in new deposits maintained for months. For most humans, the realistic tiers are $325–$700 for $15,000–$50,000 in deposits.
Requirements: Tiered — $15k/$50k/$200k in new money, maintained 60+ days.
Best for: High-balance savers moving serious money anyway.
Trap to avoid: Chasing the headline tier with money you can’t afford to park. The mid-tiers are the actual deal for normal humans.
4. Best for big direct deposits: KeyBank — up to $500
Key Select Checking pays $500 when you deposit $5,000+ in eligible direct deposits within 90 days. If your paycheck is already $2,500+ biweekly, you’ll clear this without thinking about it.
Requirements: $5,000 in direct deposits within 90 days.
Best for: Salaried workers with solid paychecks.
Trap to avoid: The $25 monthly fee — waivable with $3,000+ monthly direct deposits or $15,000 combined balances. Set up the waiver on day one.
5. Best online-only: SoFi Checking and Savings — up to $450
SoFi pays up to $450: $400 for $5,000+ in direct deposits within 25 days ($50 for $1,000–$4,999), plus small stackable extras. Zero account fees, zero overdraft fees, 55,000+ ATMs. The 25-day window is tight — have your direct deposit ready to switch BEFORE you open.
Requirements: $5,000 in eligible direct deposits within 25 days for the full $400.
Best for: Digital-first savers who want a keeper account, not just a bonus grab.
Trap to avoid: The short 25-day fuse — payroll changes can take 1-2 pay cycles. Time it right.
6. Best easy regional: BMO — $600
BMO’s $600 checking bonus is one of the largest with genuinely achievable requirements (direct deposit setup, no six-figure balance). Availability is the catch — BMO’s footprint is strongest in the Midwest and West, so check eligibility in your state first.
Best for: Anyone in BMO’s footprint wanting maximum dollars per unit of effort.
Trap to avoid: Geographic restrictions — confirm you’re eligible before applying.
7. Best Midwest value: Huntington — up to $600
Huntington regularly runs up to $600 checking bonuses with straightforward direct-deposit requirements. Like BMO, it’s a regional powerhouse — if you’re in their states, this is free money with a friendly bank attached.
Best for: Midwest residents.
Trap to avoid: State availability; offers rotate, so grab it while it’s live.
8. Best via portal: Chime — $425 through Swagbucks
Here’s the hunter’s secret: cashback portals like Swagbucks and MyPoints pay $390–$426 when you open Chime through their link and receive $200+ in direct deposit. The bank pays the portal, the portal pays you. Stack portals against direct bank offers and take whichever is higher.
Requirements: Open via portal link + $200 direct deposit.
Best for: Portal-savvy hunters who already use Swagbucks/MyPoints.
Trap to avoid: Portal bonuses can take 30+ days to credit — screenshot everything.
9. Best savings bonus: Raisin — up to $1,000
Not a checking bonus, but too big to ignore: Raisin’s marketplace pays up to $1,000 when you place $10,000+ in a partner savings account (like Western Alliance at 3.80% APY) for 90 days. Bonus + high yield on your own money = double win.
Requirements: $10,000+ in new savings deposits held 90 days; first deposit by the offer deadline.
Best for: Savers with $10k+ who want yield AND a bonus.
Trap to avoid: The 90-day lock — don’t use emergency fund money you’ll need sooner.
10. Best fast-and-simple: Wells Fargo — $325–$500
Wells Fargo’s Everyday Checking pays $325 (with promos reaching $500) for $1,000 in direct deposits. Enormous branch network if you ever need a human, and the requirements are middle-of-the-road fair.
Requirements: $1,000 in direct deposits within 90 days.
Best for: Anyone who wants branches + a bonus without extreme requirements.
Trap to avoid: The $10 monthly fee — waivable with $500 monthly direct deposit or $1,500 balance.
Compare All 10 at a Glance
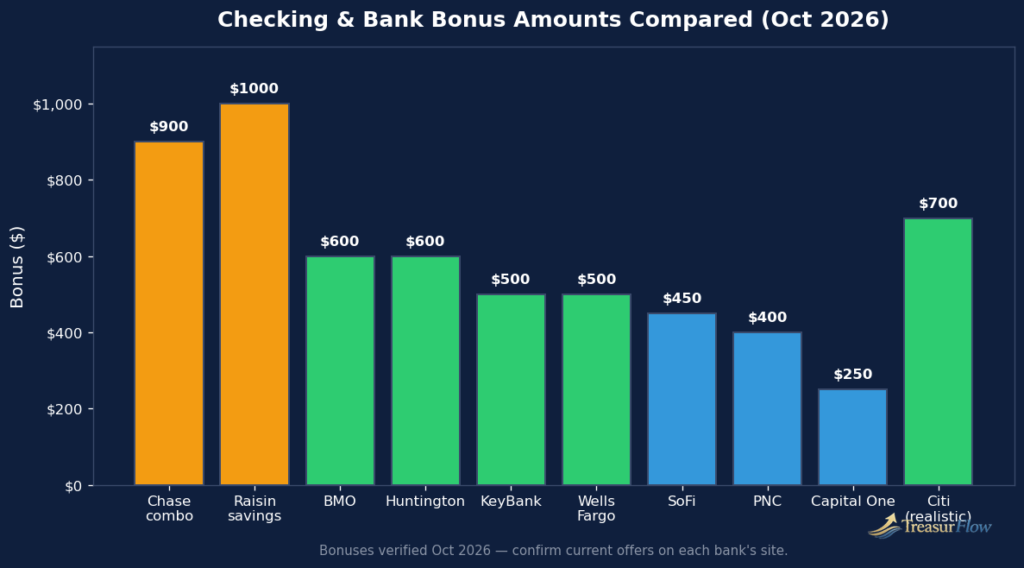
| Bank | Bonus | Key Requirement | Monthly Fee | Best For |
|---|---|---|---|---|
| Chase | $400 ($900 combo) | Direct deposit | $15 (waivable) | Best overall |
| Capital One | $250 | 2x $500 direct deposits | $0 | Easiest |
| Citi | Up to $1,500 | Tiered deposits to $200k | Varies | Biggest headline |
| KeyBank | Up to $500 | $5k direct deposit / 90 days | $25 (waivable) | Big paychecks |
| SoFi | Up to $450 | $5k direct deposit / 25 days | $0 | Online-only |
| BMO | $600 | Direct deposit | Varies | Easy regional |
| Huntington | Up to $600 | Direct deposit | Varies | Midwest |
| Chime (portal) | $425 | $200 direct deposit via portal | $0 | Portal stackers |
| Raisin | Up to $1,000 | $10k savings / 90 days | $0 | Savers |
| Wells Fargo | $325–$500 | $1k direct deposit / 90 days | $10 (waivable) | Branches |
Bonuses verified October 2026. Offers expire or change — confirm on the bank’s site.
How Bonus Hunting Actually Works (5 Steps)
1. Pick 2–3 bonuses that fit your life. Don’t chase all ten. Match requirements to your actual paycheck size and direct-deposit flexibility.
2. Check ChexSystems first (see below). Too many recent account openings can get you denied. Space applications 2–3 months apart.
3. Open and fund. Apply online (10 minutes), link your current bank, set up the required direct deposit IMMEDIATELY — payroll changes take 1–2 cycles.
4. Meet requirements and wait. Most bonuses post 10–90 days after you qualify. Screenshot every confirmation page.
5. Decide: keep or close. Great account? Keep it. Pure bonus grab? Wait out any early-termination period (usually 90–180 days), then close cleanly.
ChexSystems: The Gatekeeper Nobody Warns You About
ChexSystems is like a credit report, but for bank accounts. Banks check it when you apply — too many recent account openings, or a past account closed with unpaid fees, and you’ll be denied before the bonus conversation even starts.
What to know:
- You’re entitled to a free ChexSystems report every 12 months — pull it before a hunting spree.
- Most bonus applications are a soft pull (no credit score impact). A few banks hard-pull — check Doctor of Credit’s bank-by-bank list first.
- If you’ve been denied: our no-credit-check bank accounts guide lists second-chance options that skip ChexSystems.
- Rule of thumb: max 2–3 new bank accounts per 6 months to stay under sensitivity radar.
Taxes: The 1099-INT Surprise
Bank bonuses are taxable income — the IRS treats them like interest. Earn $10+ and the bank sends you (and the IRS) a 1099-INT. That $900 Chase combo? Expect to owe ~$200 in federal tax at a 22% bracket.
Plan for it: mentally haircut every bonus by your marginal tax rate. A $500 bonus at 22% is really $390. Still free money — just don’t spend the tax man’s share.
5 Traps That Eat Your Bonus
1. The monthly fee ambush. A $15/month fee on an account you opened for a $400 bonus costs $180/year if you forget the waiver requirements. Set calendar reminders for every fee-waiver condition.
2. “Direct deposit” doesn’t always mean YOUR deposit. Most banks require real payroll/government direct deposits — not transfers from your own other bank account. Some banks are lenient (ACH pushes count); others aren’t. When in doubt, use real payroll.
3. Early termination fees. Close a bonus account within 90–180 days and some banks claw back the bonus or charge $25–$50. Read the account agreement’s fine print before closing.
4. State restrictions. Regional bonuses (BMO, Huntington) may deny out-of-footprint applicants. Confirm eligibility for YOUR address first.
5. The “new money” rule. Savings bonuses usually require money that’s new to the bank — shuffling cash between your existing accounts at the same bank doesn’t count.
When Bonus Hunting Is NOT Worth It
- Your ChexSystems report is a mess. Get denied twice and you’re burning inquiries. Fix the underlying issues first.
- You can’t meet requirements honestly. Faking direct deposits or gaming the system can get accounts closed and bonuses clawed back.
- You’ll forget the account exists. An unmonitored account with fees is a liability, not an asset. If you’re not organized, skip it.
- The effective hourly rate is bad FOR YOU. A $200 bonus requiring $15,000 parked for 6 months plus 10 debit transactions monthly? Your time has value too.
The 12-Month Bonus Stacking Calendar (Example: ~$2,150)
| Months | Move | Bonus |
|---|---|---|
| Jan–Mar | Chase Total Checking ($400) | $400 |
| Apr–Jun | Capital One 360 ($250) | $250 |
| Jul–Sep | SoFi ($400) | $400 |
| Oct–Dec | Wells Fargo ($500) | $500 |
| Anytime | Raisin savings ($10k, $1,000) | $1,000* |
*Requires $10k parked 90 days — only if the cash is truly idle.
Total: ~$2,150 in a year, minus ~$475 in taxes = ~$1,675 net for maybe 6 hours of work. That’s a $279/hour side hustle with zero skill required.
Frequently Asked Questions
Do I have to pay taxes on bank account bonuses?
Yes. The IRS treats bank bonuses as interest income. If you earn $10 or more, the bank issues a 1099-INT and you owe federal (and possibly state) income tax on it. A $500 bonus at a 22% tax bracket nets you about $390 after tax — still excellent, just plan for the bill.
What is ChexSystems and can it block my bonus?
ChexSystems is a consumer reporting agency that tracks your banking history — account openings, closures, unpaid fees. Banks check it when you apply for new accounts. Too many recent openings or a negative record can get you denied. You get one free report per year; check it before bonus hunting, and space new accounts 2–3 months apart.
Do bank bonuses require direct deposit?
Most do, but not all. Typical requirements range from $500 to $5,000 in qualifying direct deposits within 25–90 days. “Qualifying” usually means real payroll or government deposits — transfers from your own accounts often don’t count. A few offers have lighter or no direct-deposit requirements.
How long does it take to receive a bank bonus?
Usually 10 to 90 days after you meet all requirements. Chase is famously fast (often around 10 business days); others make you wait the full qualification period plus processing time. Always screenshot your offer terms and requirement confirmations in case you need to follow up.
Can I get more than one bank bonus?
Absolutely — that’s the entire strategy. There’s no legal limit. The practical limits are ChexSystems sensitivity (space applications out), your ability to meet each offer’s requirements, and your organizational skills. Many hunters earn $1,500–$2,500 per year across 3–5 bonuses.
Are bank bonuses only for new customers?
Almost always, yes. “New customer” typically means you haven’t held that account type at that bank in the last 12–24 months (varies by bank). Existing customers are excluded — which is exactly why rotating through different banks is the core hunting strategy.
Do bank account applications hurt my credit score?
Usually not. Most banks do a soft pull (or only check ChexSystems), which doesn’t affect your score. A minority do hard pulls — research each bank beforehand. Either way, opening bank accounts doesn’t create the credit-utilization impact that credit cards do.
What disqualifies me from a bank bonus?
The big five: (1) you’re an existing customer, (2) you fail the direct-deposit requirement, (3) negative ChexSystems record, (4) you live outside the bank’s footprint, (5) you close the account before the bonus posts. Read the offer’s fine print — disqualifiers are always listed.
Can I close the account right after getting the bonus?
You can, but check the early-termination terms first. Many banks claw back the bonus or charge a fee if you close within 90–180 days. The safe play: keep the account fee-free for 6 months, then close cleanly if you don’t want it.
Do bank bonuses affect my credit score?
No direct effect — bonuses aren’t credit products. The only indirect risk is a hard inquiry at the small minority of banks that hard-pull, which costs a few points temporarily. ChexSystems inquiries don’t touch your FICO score at all.
The Bottom Line
Banks are spending billions to buy customers — $39,000+ in ad creatives in our research alone — and bonus hunting just redirects some of that marketing budget into YOUR pocket. $1,500–$2,500 a year in effectively free money for a few hours of organized effort is the best hourly rate in personal finance.
Start with ONE easy win (Capital One’s $250 is the perfect training wheels), nail the requirements, watch the bonus post, and decide if you want to run the full calendar. Verify every offer on the bank’s site, respect ChexSystems, budget for taxes — and enjoy getting paid to open bank accounts.

Muhammad Zakir is the founder of Treasurflow and the author of its personal finance guides. He researches consumer banking, credit, and personal loans, and every guide cites primary sources such as the CFPB, FDIC, FTC, and IRS. His content is educational and is not personalized financial advice.
3 thoughts on “Best Checking Account Bonuses 2026: 10 Picks Ranked by Bonus-Hunter Strategy”